

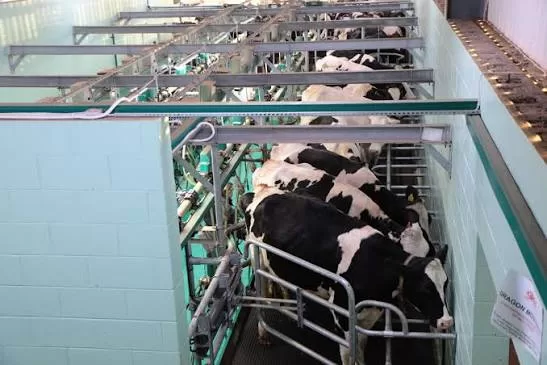
Libya’s dairy market is attracting new industrial investment as companies seek to meet strong domestic demand while reducing the country’s reliance on imported milk and dairy products. The opportunity is also relevant beyond Libya: for Gulf food companies and investors accustomed to thinking about food security across borders, the country offers a nearby market where processing capacity and the wider agricultural supply chain remain underdeveloped.
Two companies are pursuing this opportunity from opposite ends of the country. In the west, Safi Food Complex, the bottling arm of Whiba Holding, has already begun producing milk and juice at a major facility in Zliten. In the east, Zulfa Food Industries, owned by AlushibeGroup and led by Ahmed Gadalla, is developing a new plant in Benghazi equipped by Tetra Pak.
The investments point to a broader opportunity, but also raise a key question: can new factories drive domestic milk production rather than simply process imported inputs?
A growing processing industry without a growing dairy base
Libya’s domestic milk production has remained broadly stagnant even as processing capacity has increased.
United Nations figures put combined raw milk production from cows, sheep, goats and camels at approximately 237,000 tonnes in 2019, compared with around 226,000 tonnes in 2024. Over the same period, the country has continued to rely heavily on imported dairy products.
Libya imported approximately 109,200 tonnes of dairy products in 2024, with Europe accounting for much of the supply. Imports declined by roughly a quarter during the first nine months of 2025, with powder and boxed liquid milk falling while imports of condensed milk increased.
The figures suggest domestic processing may be replacing some imported packaged milk, but customs data does not establish whether inputs come from Libyan farms or imported milk powder and concentrates.
That distinction matters. Local milk creates demand for livestock, feed, veterinary services, cold-chain logistics and agricultural investment. Imported powder can localise processing while leaving the industry dependent on international suppliers and foreign currency.
The long-term economic impact will depend on which model develops.
Safi and Zulfa take different routes
Safi Food Complex provides the more established example.
In February 2024, the company opened a milk and juice factory that it described as the largest and most modern facility of its kind in Libya. Safi milk and juice products are already being sold domestically. The company is part of Whiba Holding, whose food and beverage operations span several Libyan locations.
Zulfa is pursuing a similar strategy in Benghazi. In 2025, Tetra Pak announced a €14 million greenfield project with Zulfa, a subsidiary ofAlushibe Group. The 140,000-square-metre facility is designed for integrated processing and packaging, including mixing systems, UHT and pasteurisation treatment and three initial production and filling lines. Milk and juice are among its initial product categories.
The two investments reflect a large domestic consumer base and a food market still dependent on imports.
The opportunity may also be relevant to Gulf-based investors and food companies. Gulf states have invested heavily in food security, dairy production and overseas agricultural supply chains, creating experience in areas such as integrated farming, feed, processing and cold-chain logistics. Libya’s proximity to Gulf markets and its need for greater domestic food production could make those capabilities relevant, although the commercial case will depend on infrastructure, regulation, financing and security conditions.
Their geographic positions are also significant. Safi is operating in western Libya, while Zulfa is establishing production capacity in Benghazi in the east. Both companies are responding to demand in markets that have developed under Libya’s fragmented political and economic environment.
Fragmentation remains a business cost
The expansion of food manufacturing also highlights the economic cost of Libya’s institutional fragmentation.
Different customs arrangements, banking restrictions and transport challenges can make national supply chains more expensive. A more integrated market could allow manufacturers to build a single farm-to-consumer chain.
Dairy producers see the issue from a different perspective. Feed, packaging materials, imported equipment and agricultural inputs all have to move through the same commercial environment.
Greater regulatory and financial integration could benefit processors and the wider food-manufacturing sector.
The next test is local sourcing
Zulfa’s development is particularly worth watching because Alushibe Group is moving into manufacturing from a trading background.
International supply relationships can help a new factory secure inputs quickly, but may also make continued reliance on imported dairy inputs attractive.
Safi, meanwhile, can already be assessed on the proportion of its milk production sourced domestically. Zulfa’s eventual sourcing model will become clearer as its Benghazi facility moves toward production.
That will be the key indicator.
If the new factories primarily process imported milk powder, Libya will have expanded its domestic food-processing capacity without fundamentally changing its dependence on foreign dairy supplies.
If manufacturers begin purchasing meaningful volumes of milk from Libyan farms, the impact will be considerably broader. It would create a domestic market for livestock producers and potentially encourage investment across the agricultural supply chain, from animal husbandry and feed production to refrigerated transport.
Safi and Zulfa therefore offer an early test of whether Libya can move from importing dairy products to developing an integrated domestic dairy value chain.